When considering investing in anything it is very important to step back and gain a “Big Picture” perspective regarding where a security is in its “life cycle” because, like living things, they go through an establishment phase, a growth phase, the mature phase or stage and eventually a declining phase at the end of which they either reinvent themselves or die. Thus, on a commodity or stock chart, the establishment phase corresponds to a usually long period of basing before a bull market starts, the growth phase is the actual bull market that in the case of companies that become very successful like Coca-Cola or MacDonalds can go on for years or even decades, the mature phase is often when a top area forms as the company gets increasingly threatened by competitors or its product or service goes out of fashion and lastly the declining phase when it enters a bear market often as market share and / or profits decline. We can simplify this as Stage 1: the basing phase, Stage 2: the growth phase, Stage 3: the topping phase and Stage 4: the declining phase. The reason for this preamble is that we can see most clearly on gold and silver’s very long-term charts that even though, unlike companies, they don’t get born or die, their prices do go through a 4-stage life cycle as just described which later repeats.
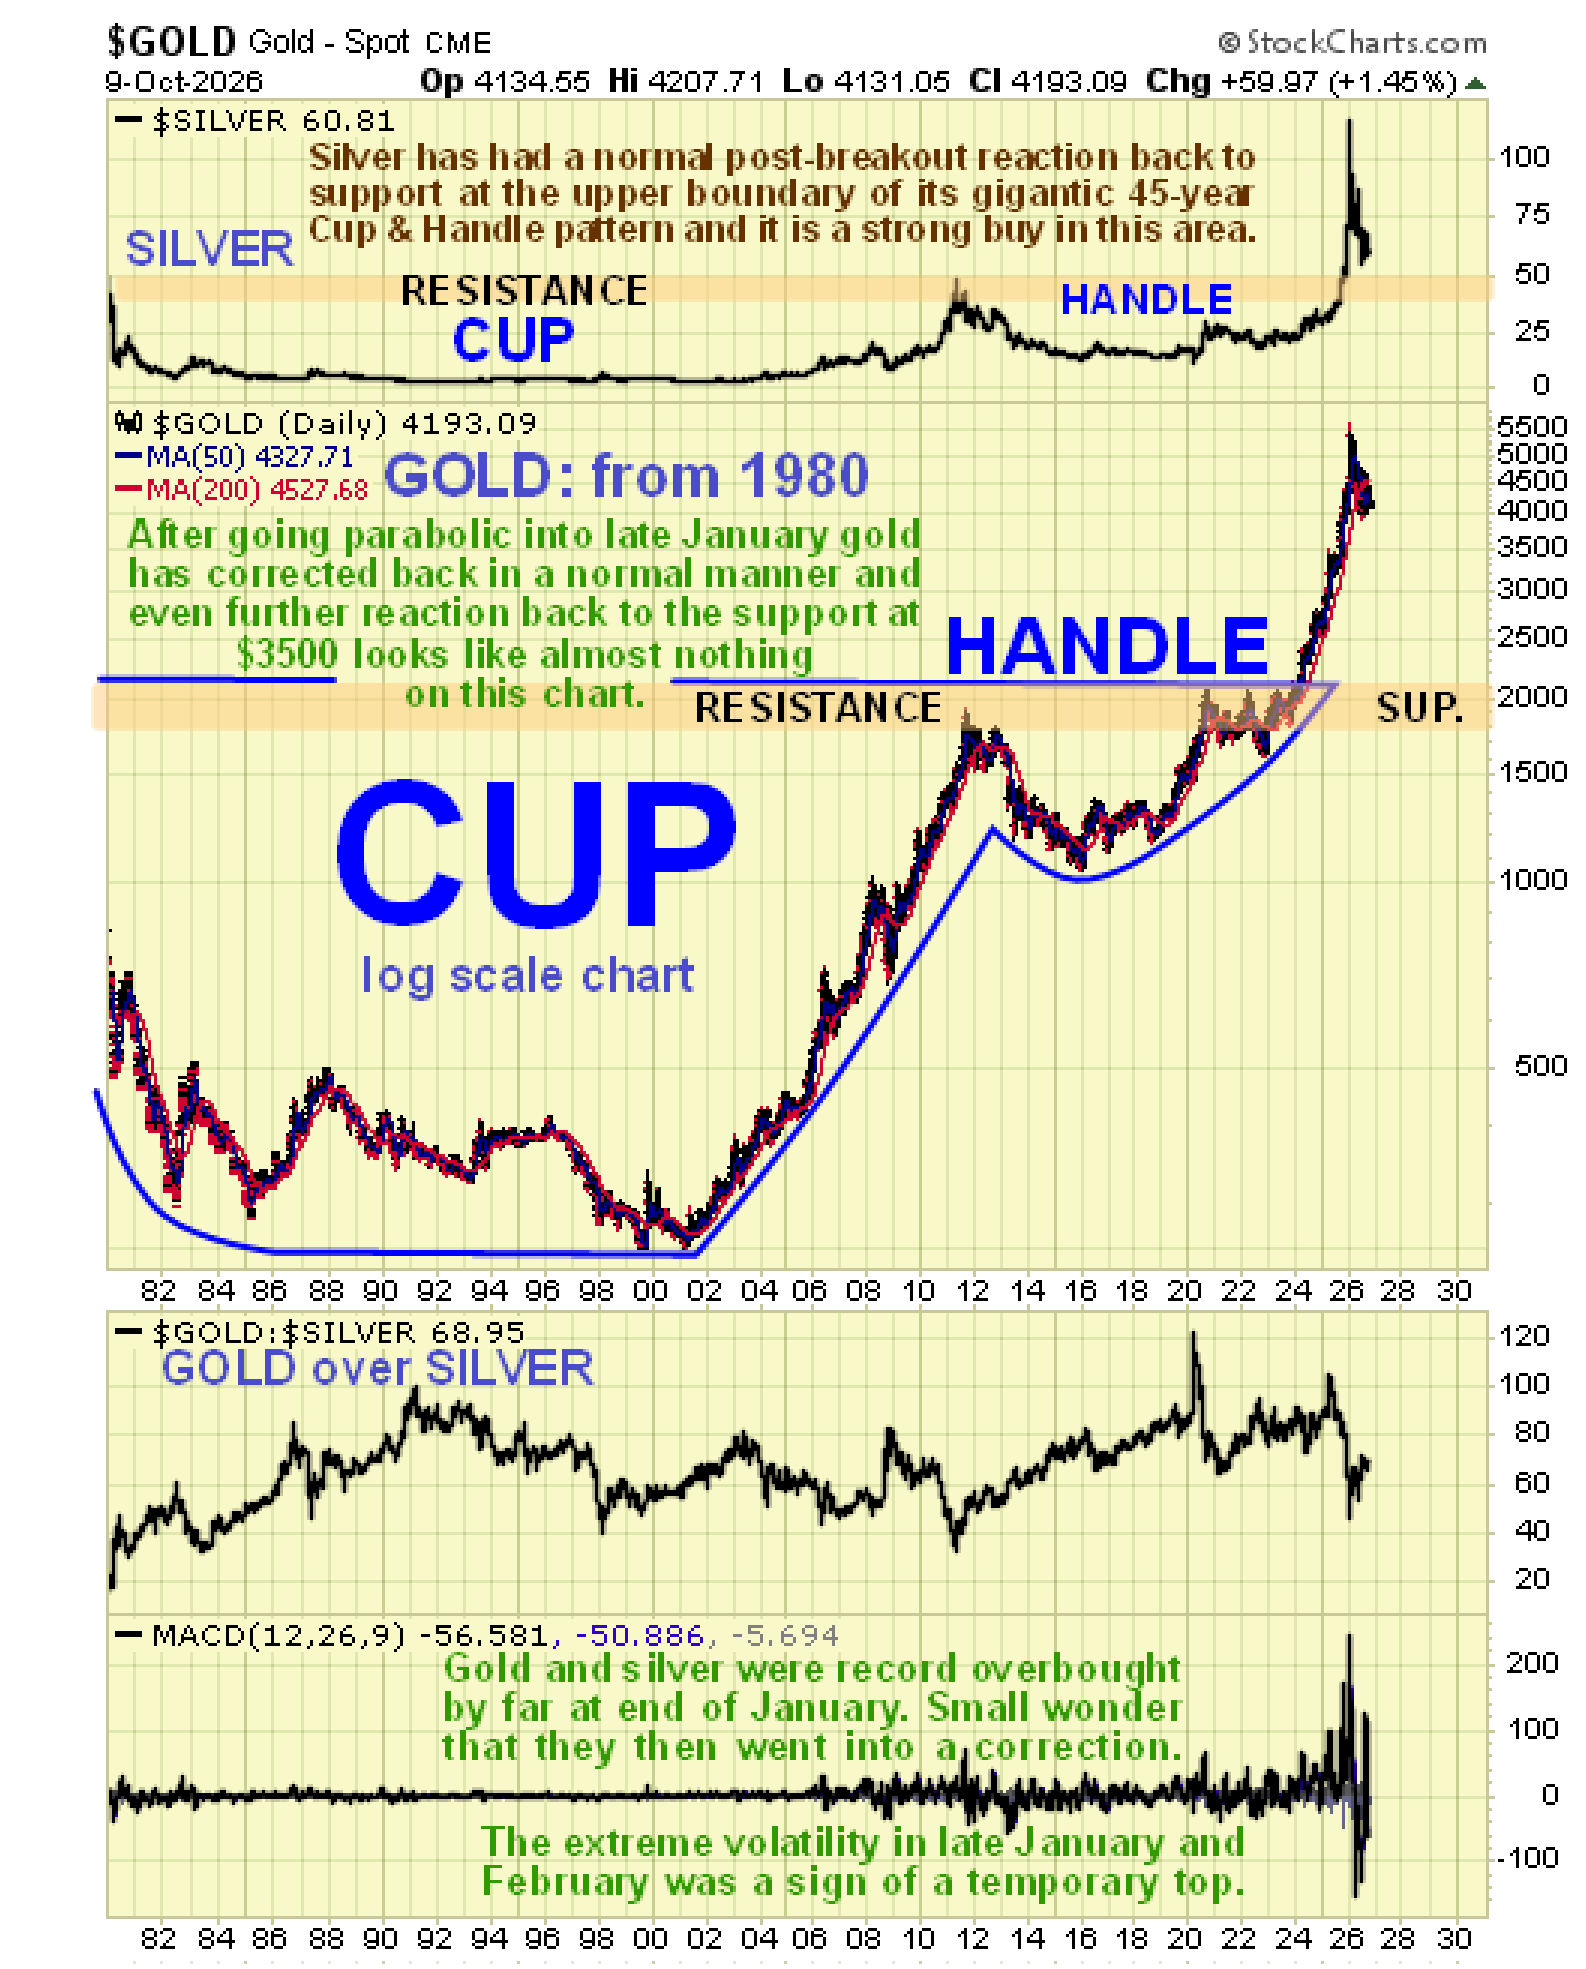
Thus, on gold’s very long-term chart going way back to about 1981 which is shown below, we can see that following its great 1970’s bull market it went into a severe Stage 4 bear market until about 1985 and even though it made lower lows in 1999 and 2001, it was essentially in a Stage 1 basing pattern from the mid 80´s through 2001. Then it began a massive Stage 2 bull market and it is important to be aware that, even though it had a major correction from its 2011 peak, this correction was just a big pause in its ongoing Stage 2 bull market which regained traction early in 2024. Now here is a very important point; bearing in mind that most fiat currencies are on course to become virtually worthless in the face of insurmountable debt,
all of the action from 1980 through early 2024 can be viewed as a gigantic Stage 1 Cup & Handle base pattern that gold only broke out of to start an unprecedented Stage 2 bull market in 2024. Once you comprehend this you realize that gold is going to fly off the top of this chart to end up at much higher levels. We can also see on this chart that gold’s correction from its late January peak has been trivial compared to the advance that preceded it. It is viewed as all but impossible for gold to drop back to the support at the top of the giant Cup & Handle pattern that it broke out of in 2024, partly because this would imply that silver would drop back below the support at the top of its very similar pattern.
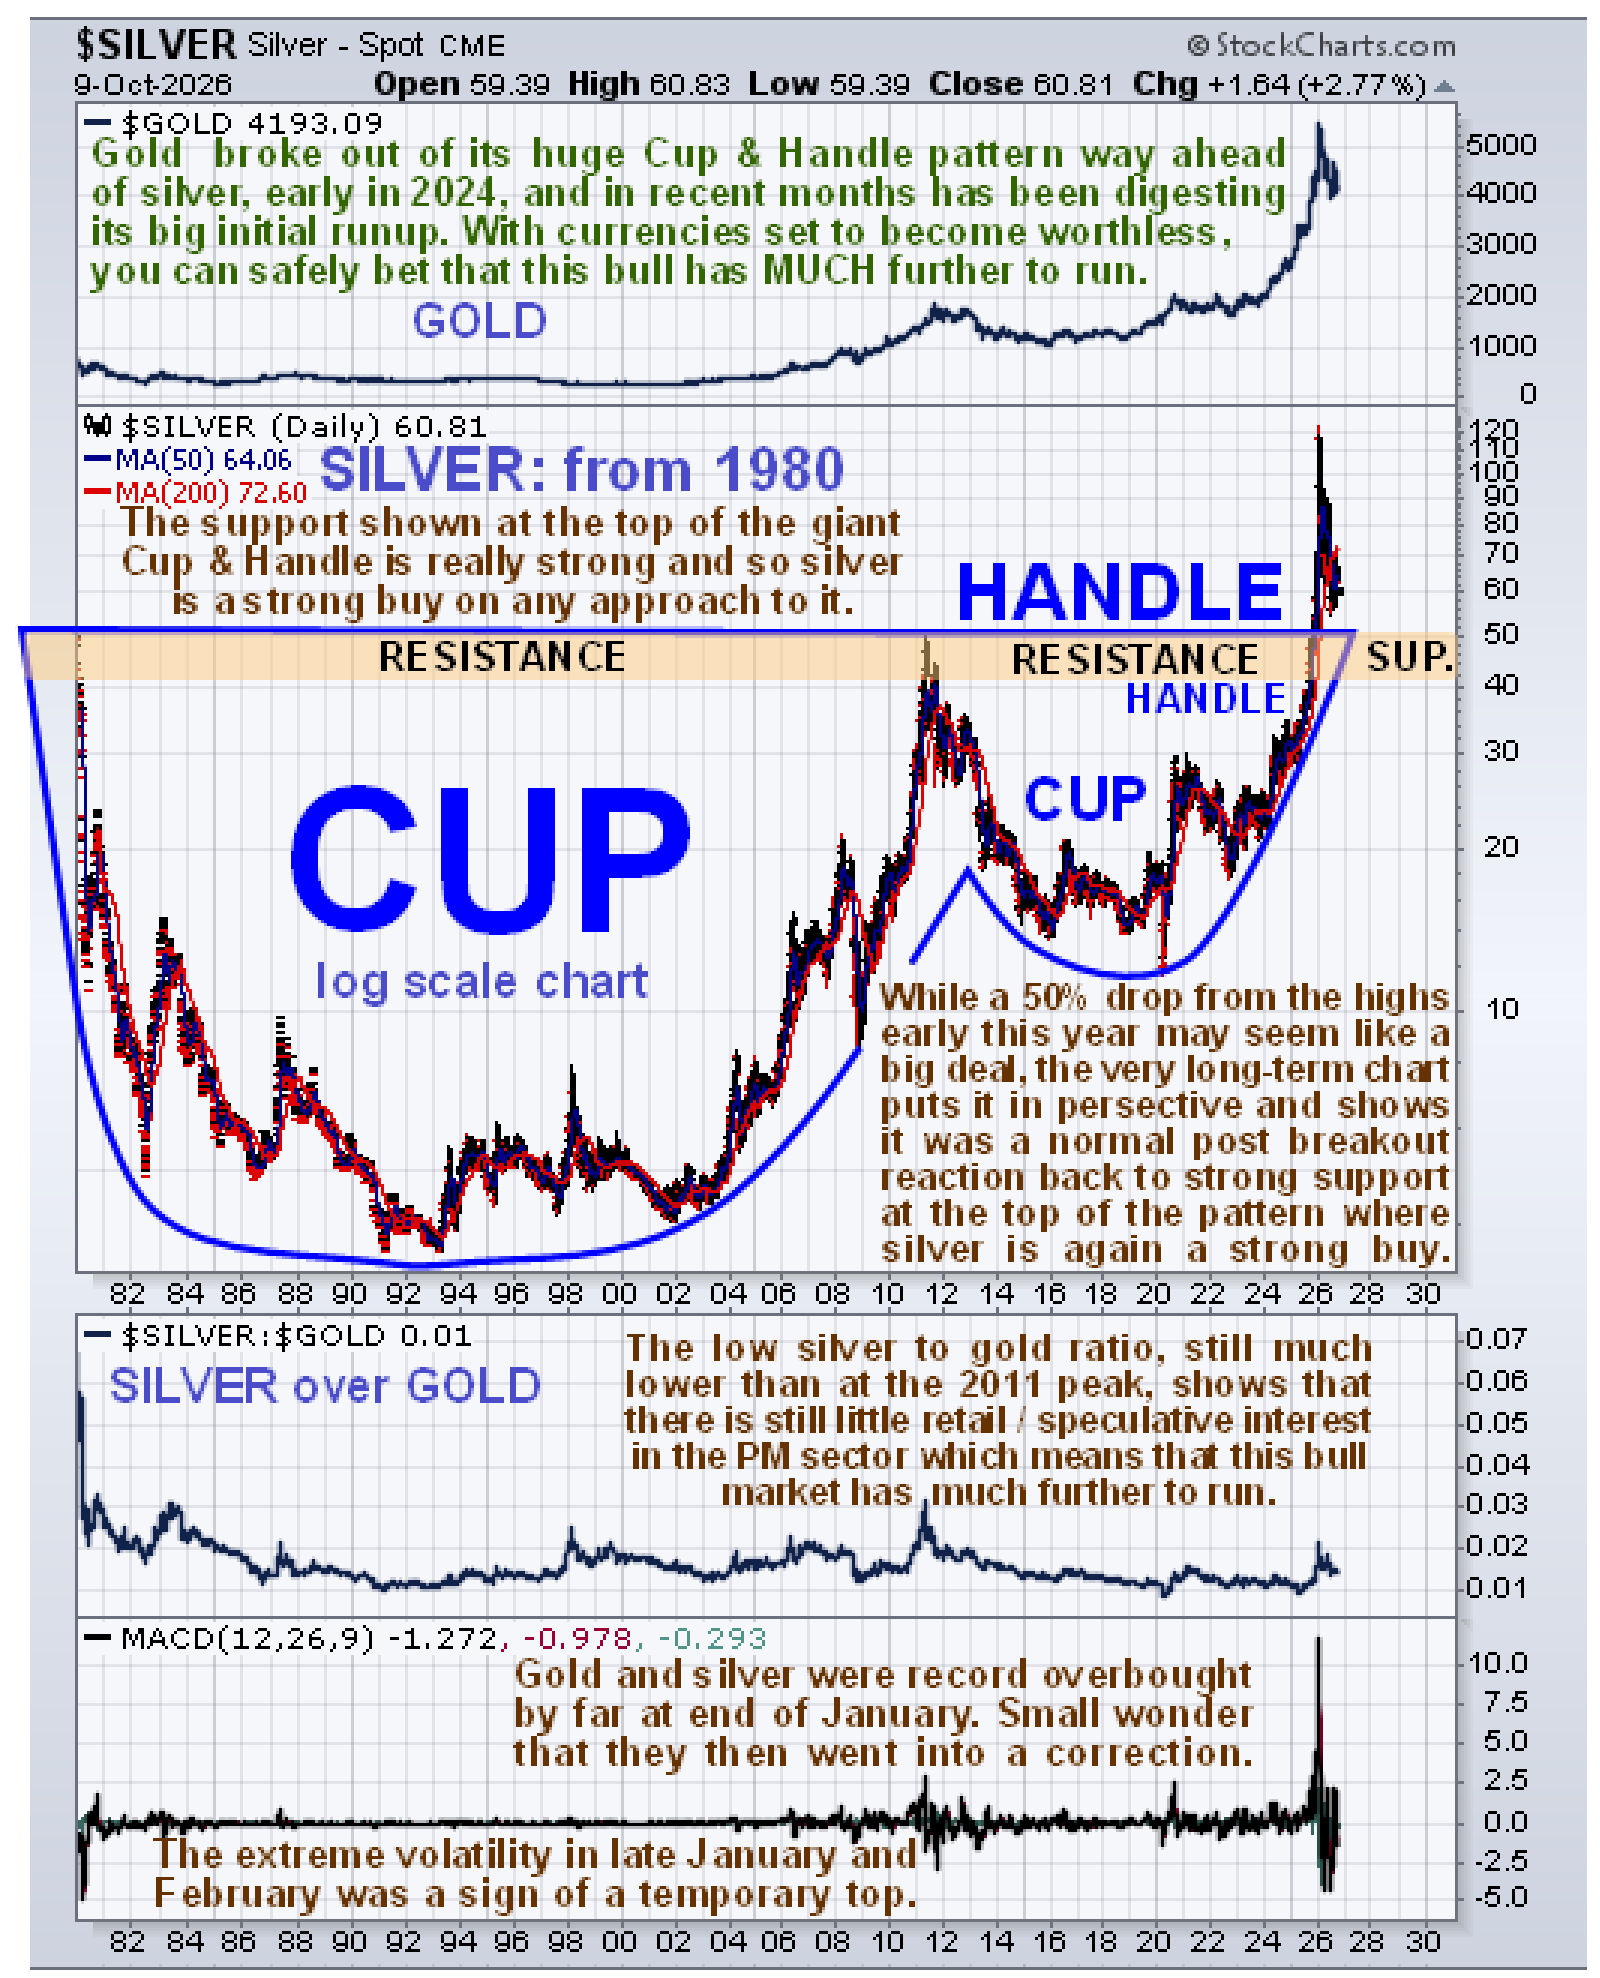
Silver’s very long-term chart going way back to about 1981 is almost identical to that of gold, the big difference being that silver did not get as far away from the top of its massive Cup & Handle pattern as gold did and it has reacted back close to its upper boundary. This is actually normal in the earlier stages of big PM sector bull markets when gold tend to perform best – silver really shines towards the later stages of the bull market. This silver chart provides us with valuable guidance because we can see that it is now back at or close to the point where it should embark on another major upleg – and it is not going to do that without gold doing likewise.
The good news doesn’t end with what we have just seen on the Big Picture, for the short-term outlook now looks positive too – why? It’s because as we will now proceed to see on shorter-term charts, both the dollar and interest rates look set to correct back following their big runups of recent weeks.
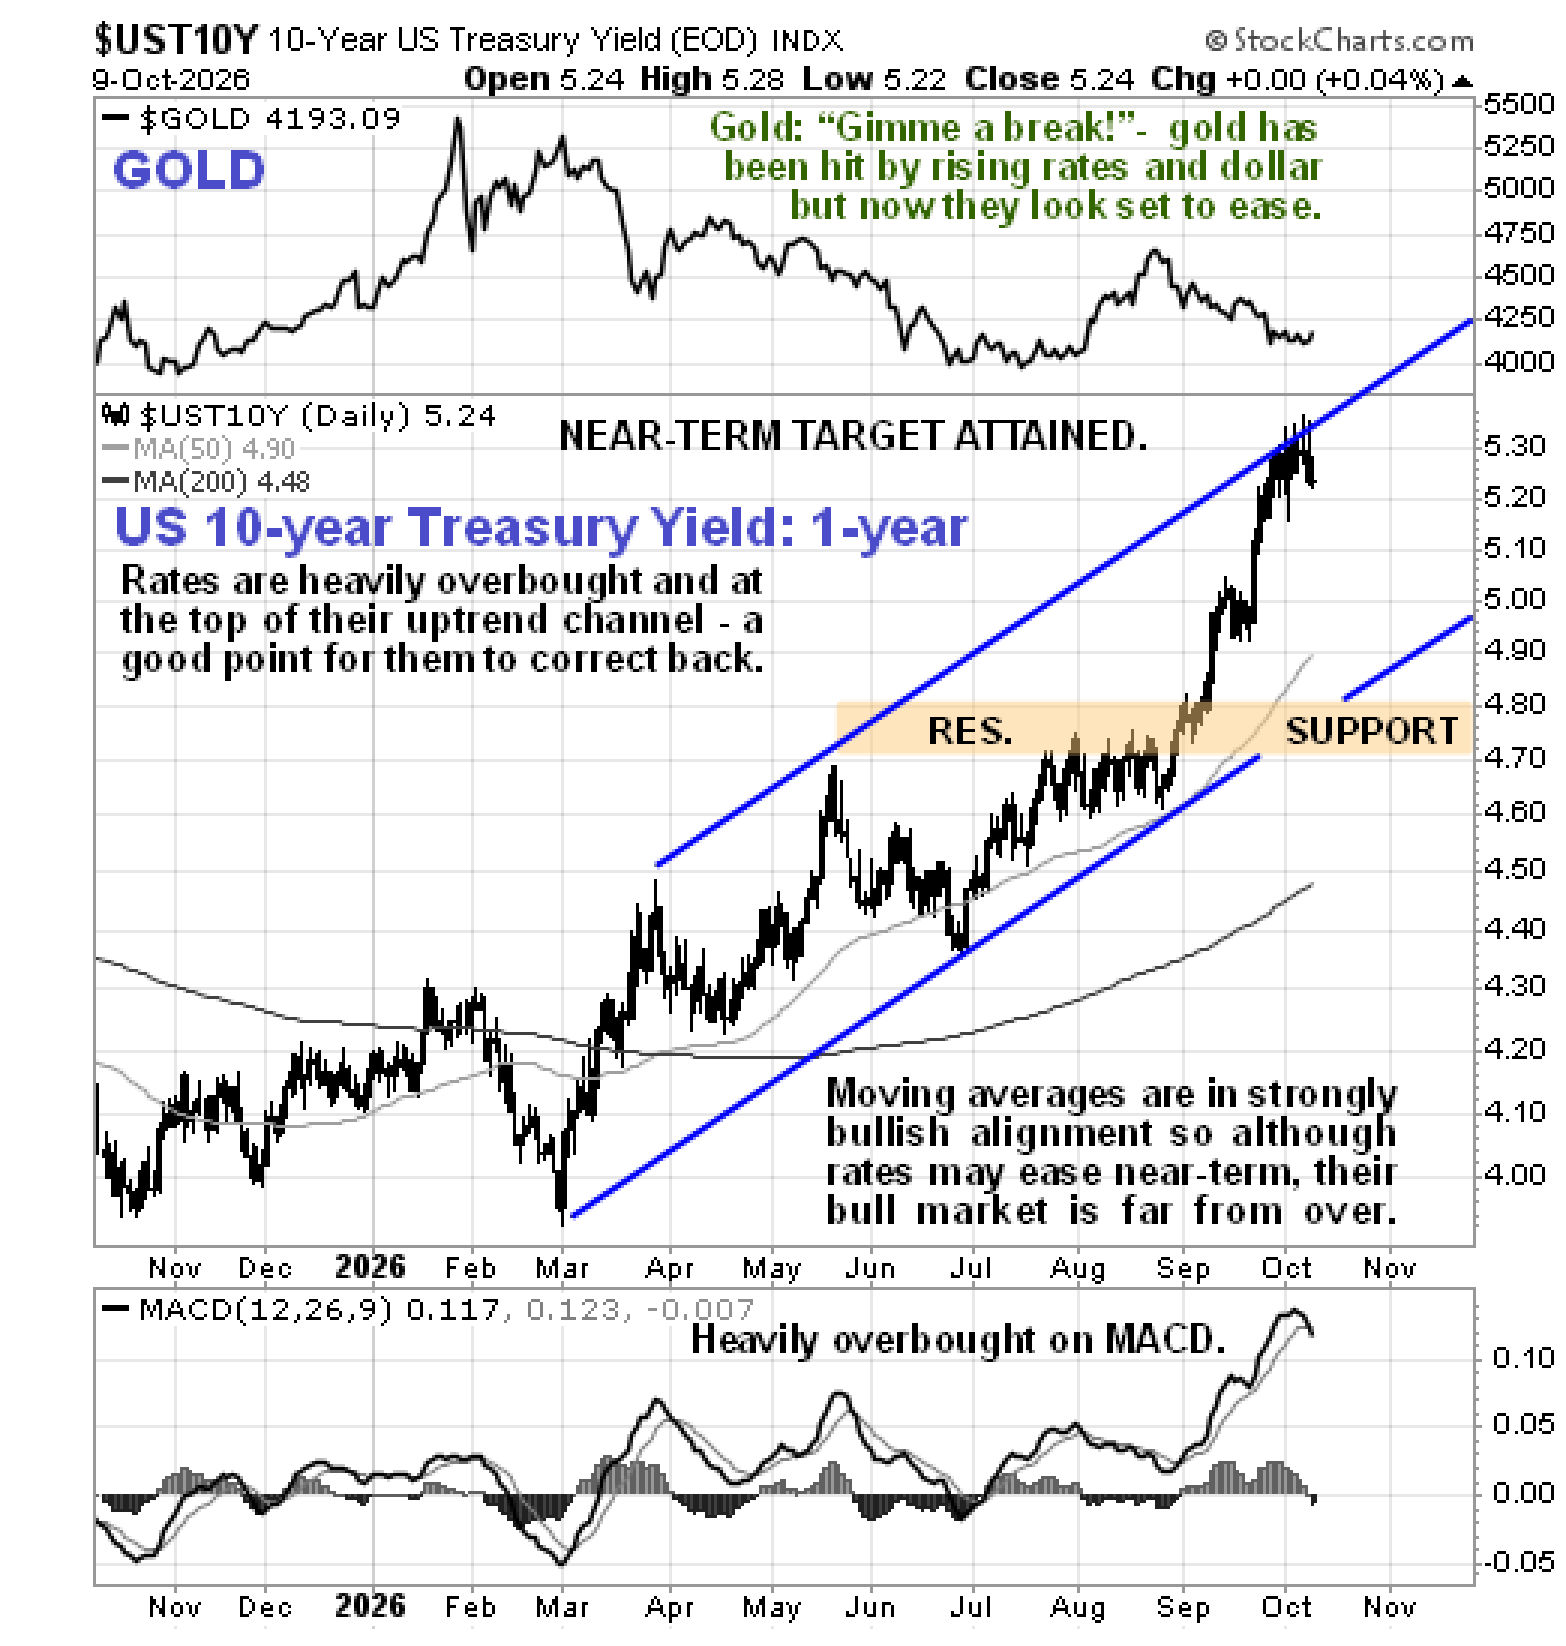
Starting with the 1-year chart for the 10-year US Treasury Yield, we see that it is currently still heavily overbought at the upper boundary of its orderly uptrend channel and thus likely to at least consolidate for a while and more probably react back across the channel, which would of course provide the perfect excuse for the PM sector to take off higher again after its recent drop.
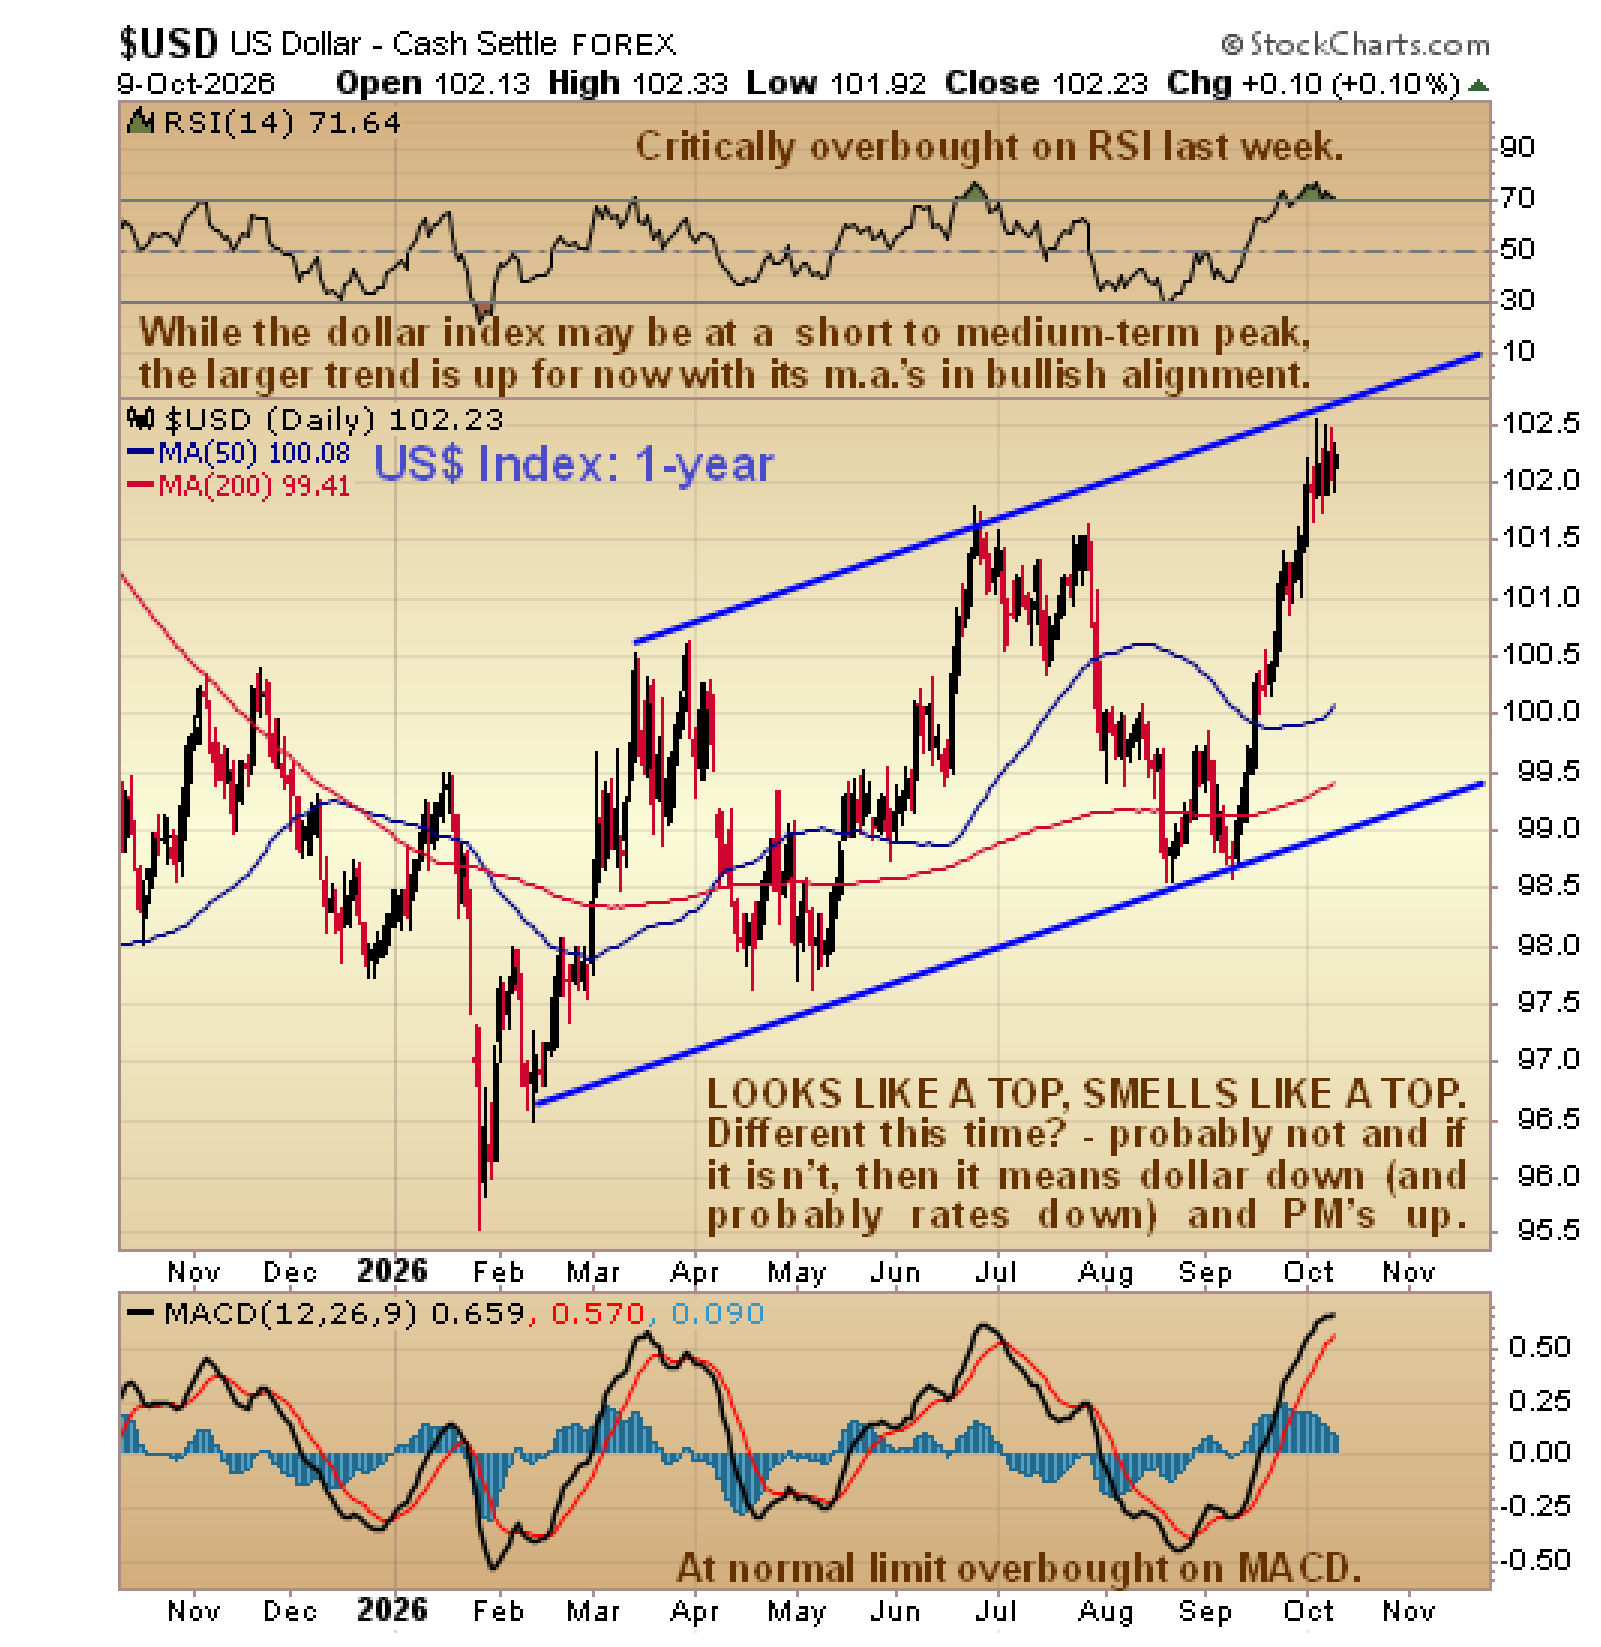
The surge in US rates has helped to drive the dollar index higher, but it too is spluttering at the upper rail of its intermediate uptrend channel and looking set to drop. Could it just carry on higher? – anything is possible but the graveyards of Wall St are full of the people who thought “it’s different this time”…
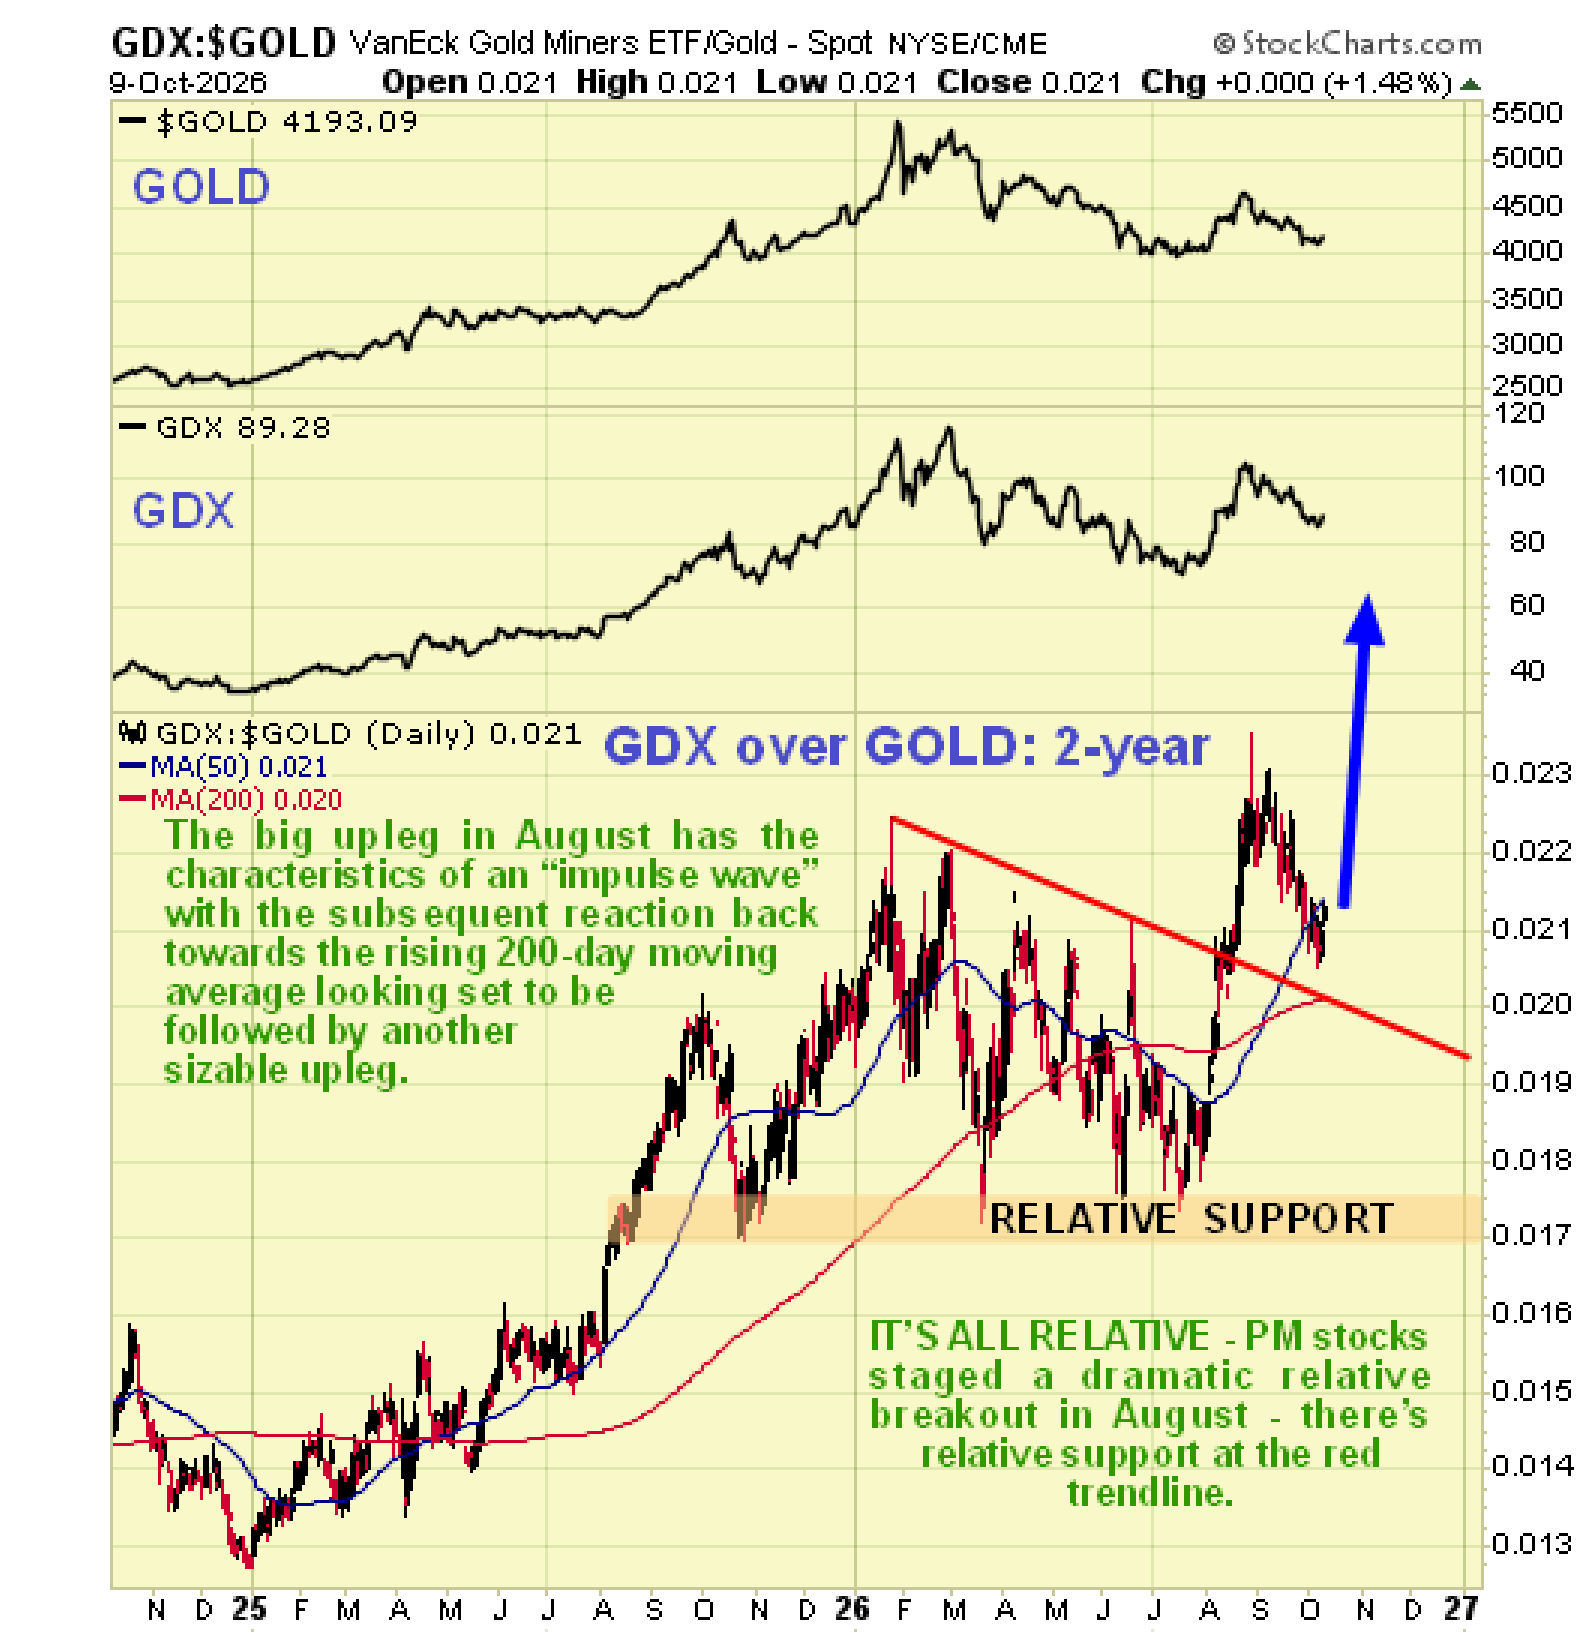
Now we are going to consider a very positive development for the PM sector that has been many years in the making. A lot of investors in the sector or would be investors and CEO’s of mining companies, especially old timers, will recall the appalling underperformance of gold and silver stocks relative to the metals themselves from about 2008 all the way through to early 2016, when interest in the sector fell to abysmally low levels. Fast forward to today when with AISC (All-in Sustaining Costs) for many producers way below current and recent gold prices, they are making money “hand over fist” and coming out with stellar results. This fact hasn’t percolated the skulls of many investors yet, but it is starting to and as more of them start to get their heads around it, we are going to see mining stocks swiftly catch up with this reality. It’s a process that has already started as we can see on the latest 2-year ratio chart for GDX over gold on which we can see that the August sector breakout saw this ratio not just break out but advance to clear new highs – meaning that stocks are starting to outperform gold on a proportional basis…
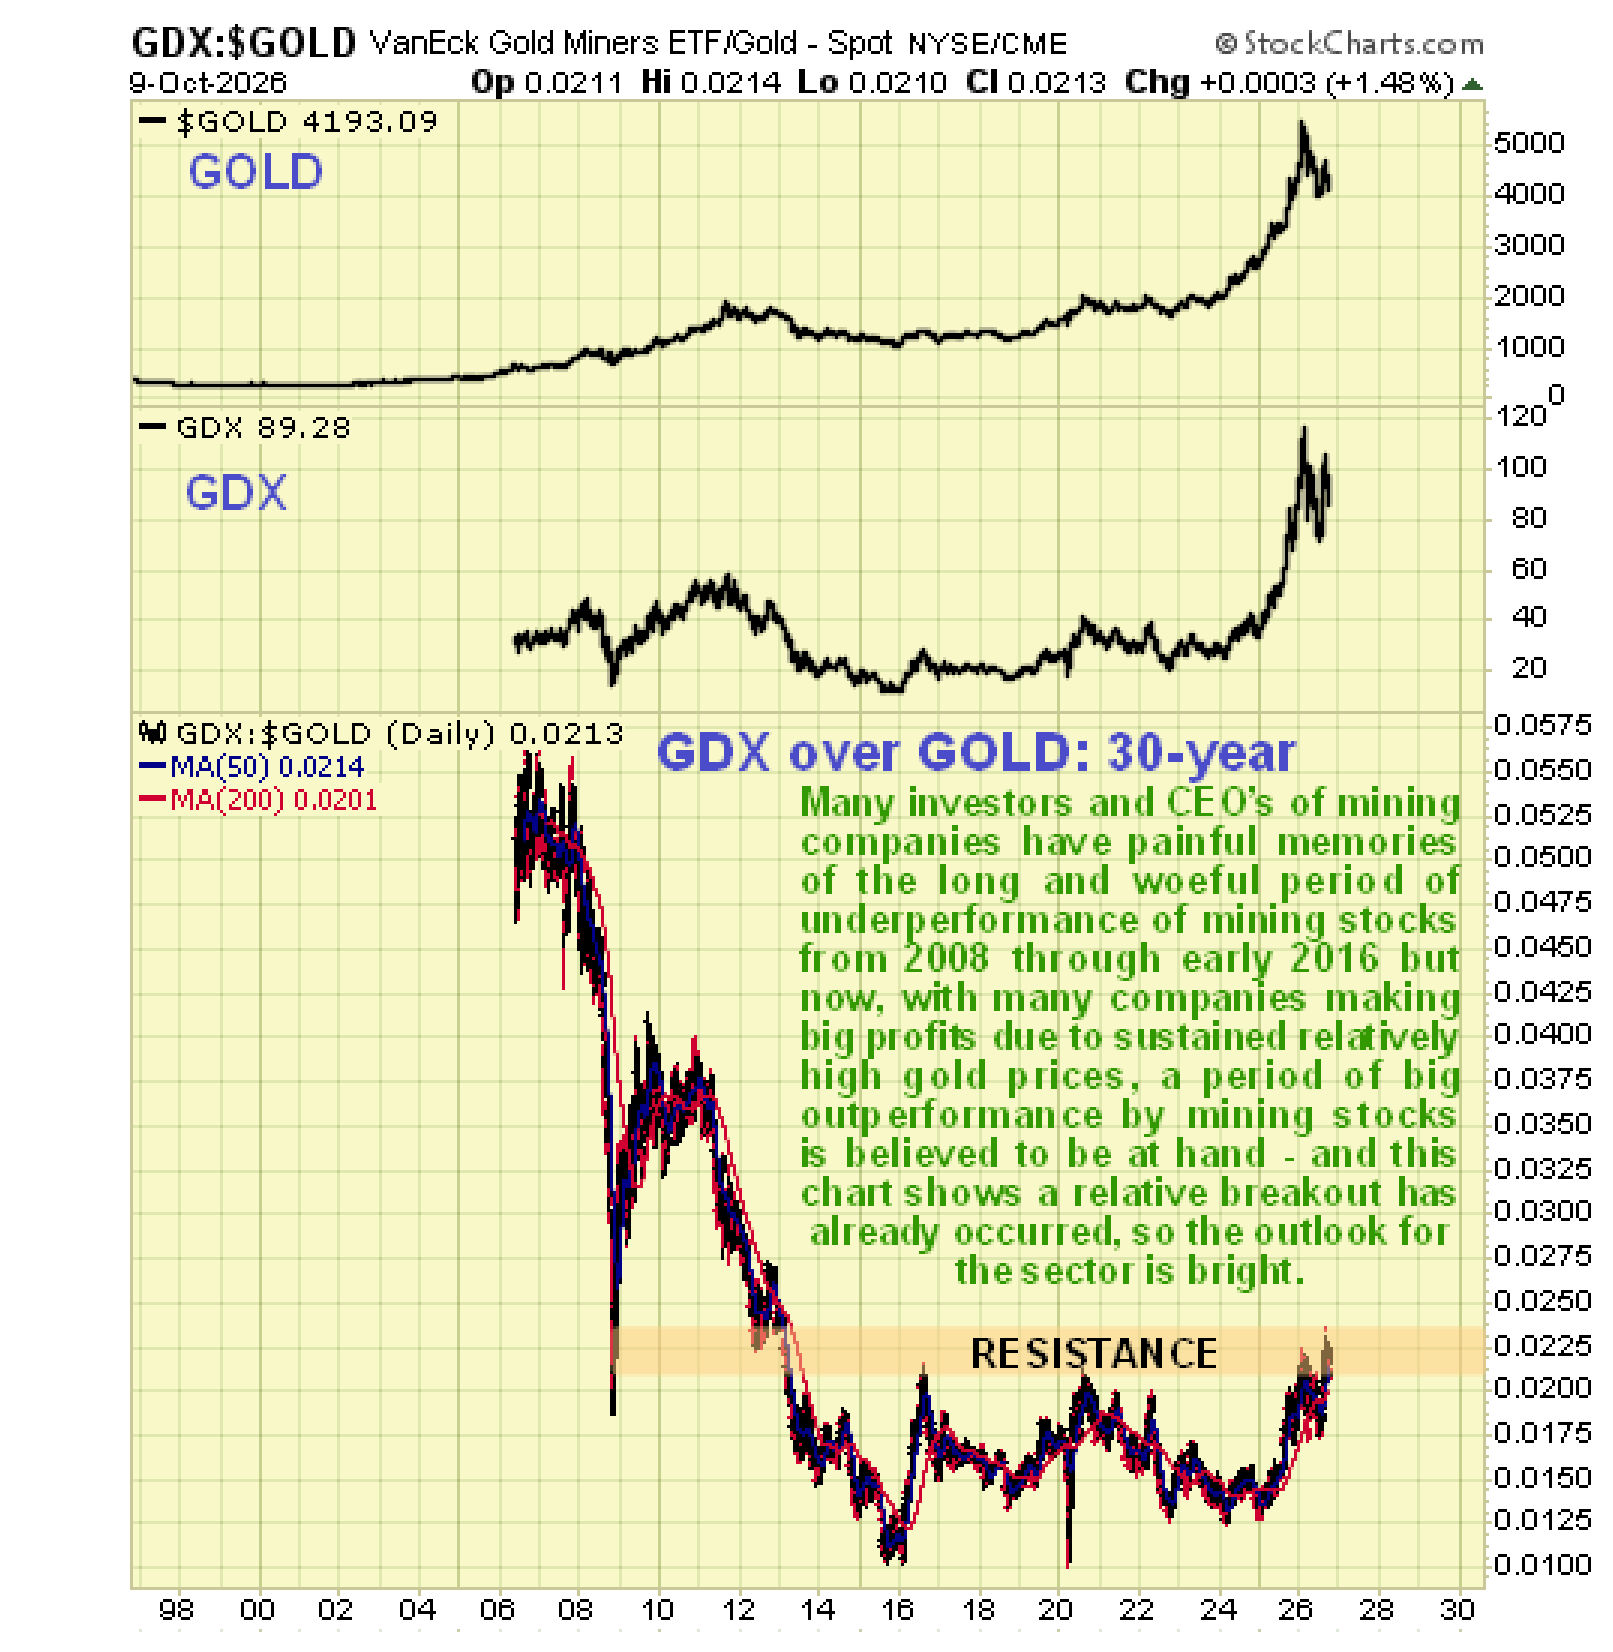
This is just the start – on the long-term chart for GDX over gold we can see that, following the appalling underperformance of gold stocks from 2008 all the way through to early 2016, mentioned above, a giant relative base pattern formed which the ratio has only started to break out of this year. On this chart we can see that gold stocks are powering up for a long period of outperformance relative to gold that has been a long time coming. If this ratio were to advance to its levels in the mid-2000’s, we are looking at huge gains for gold stocks from here.
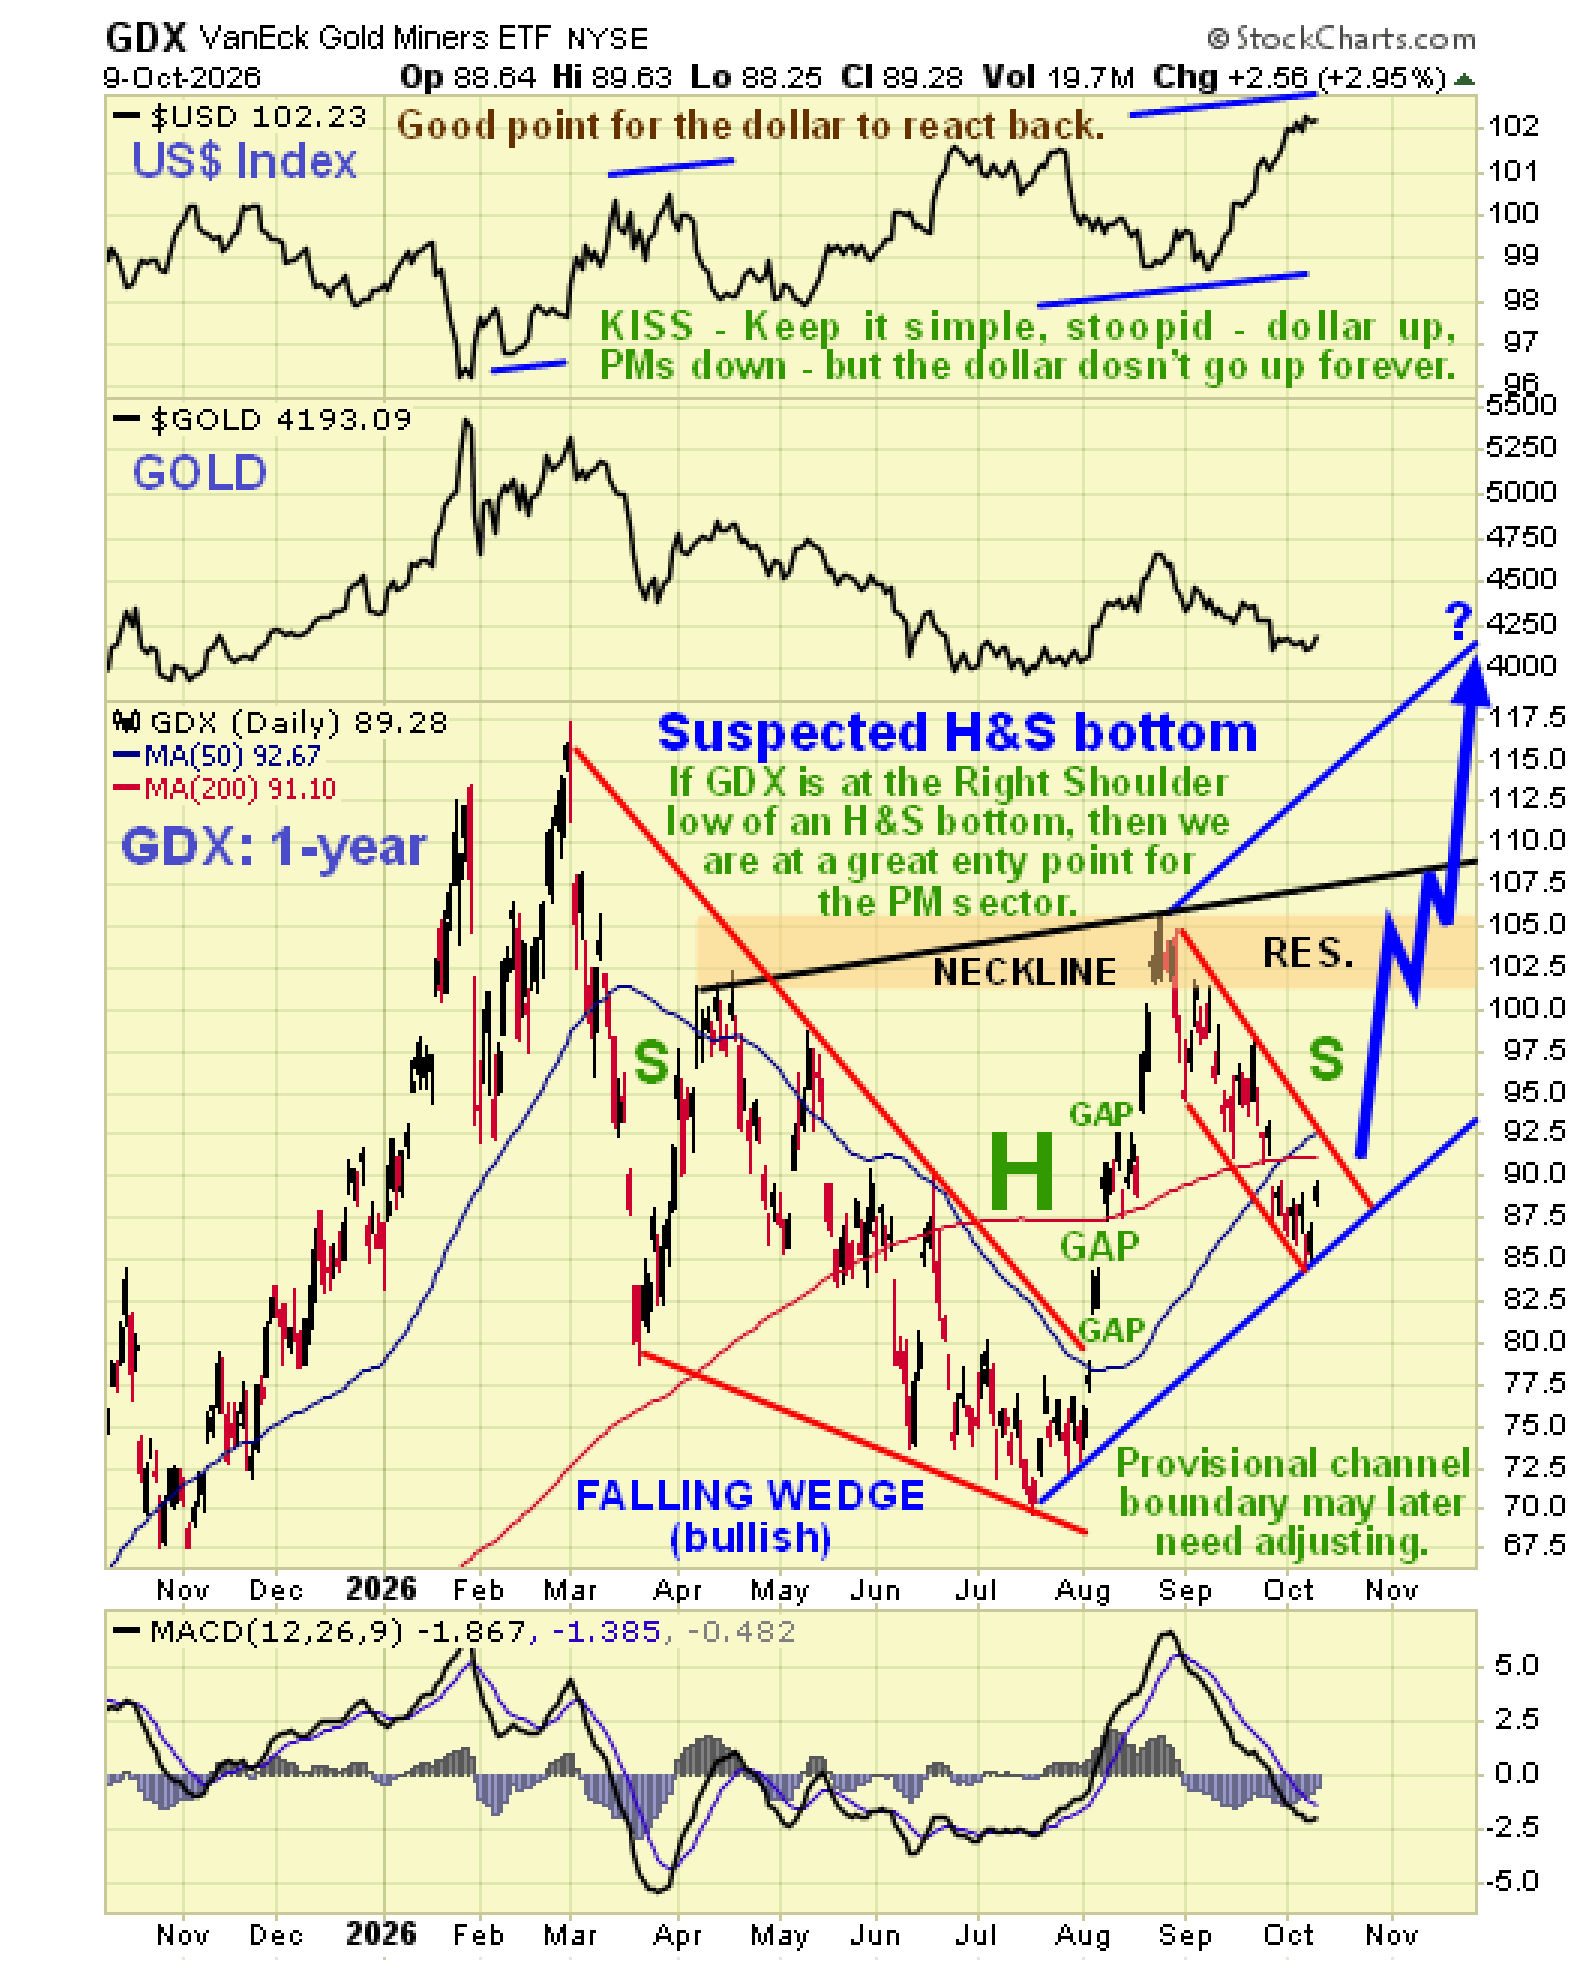
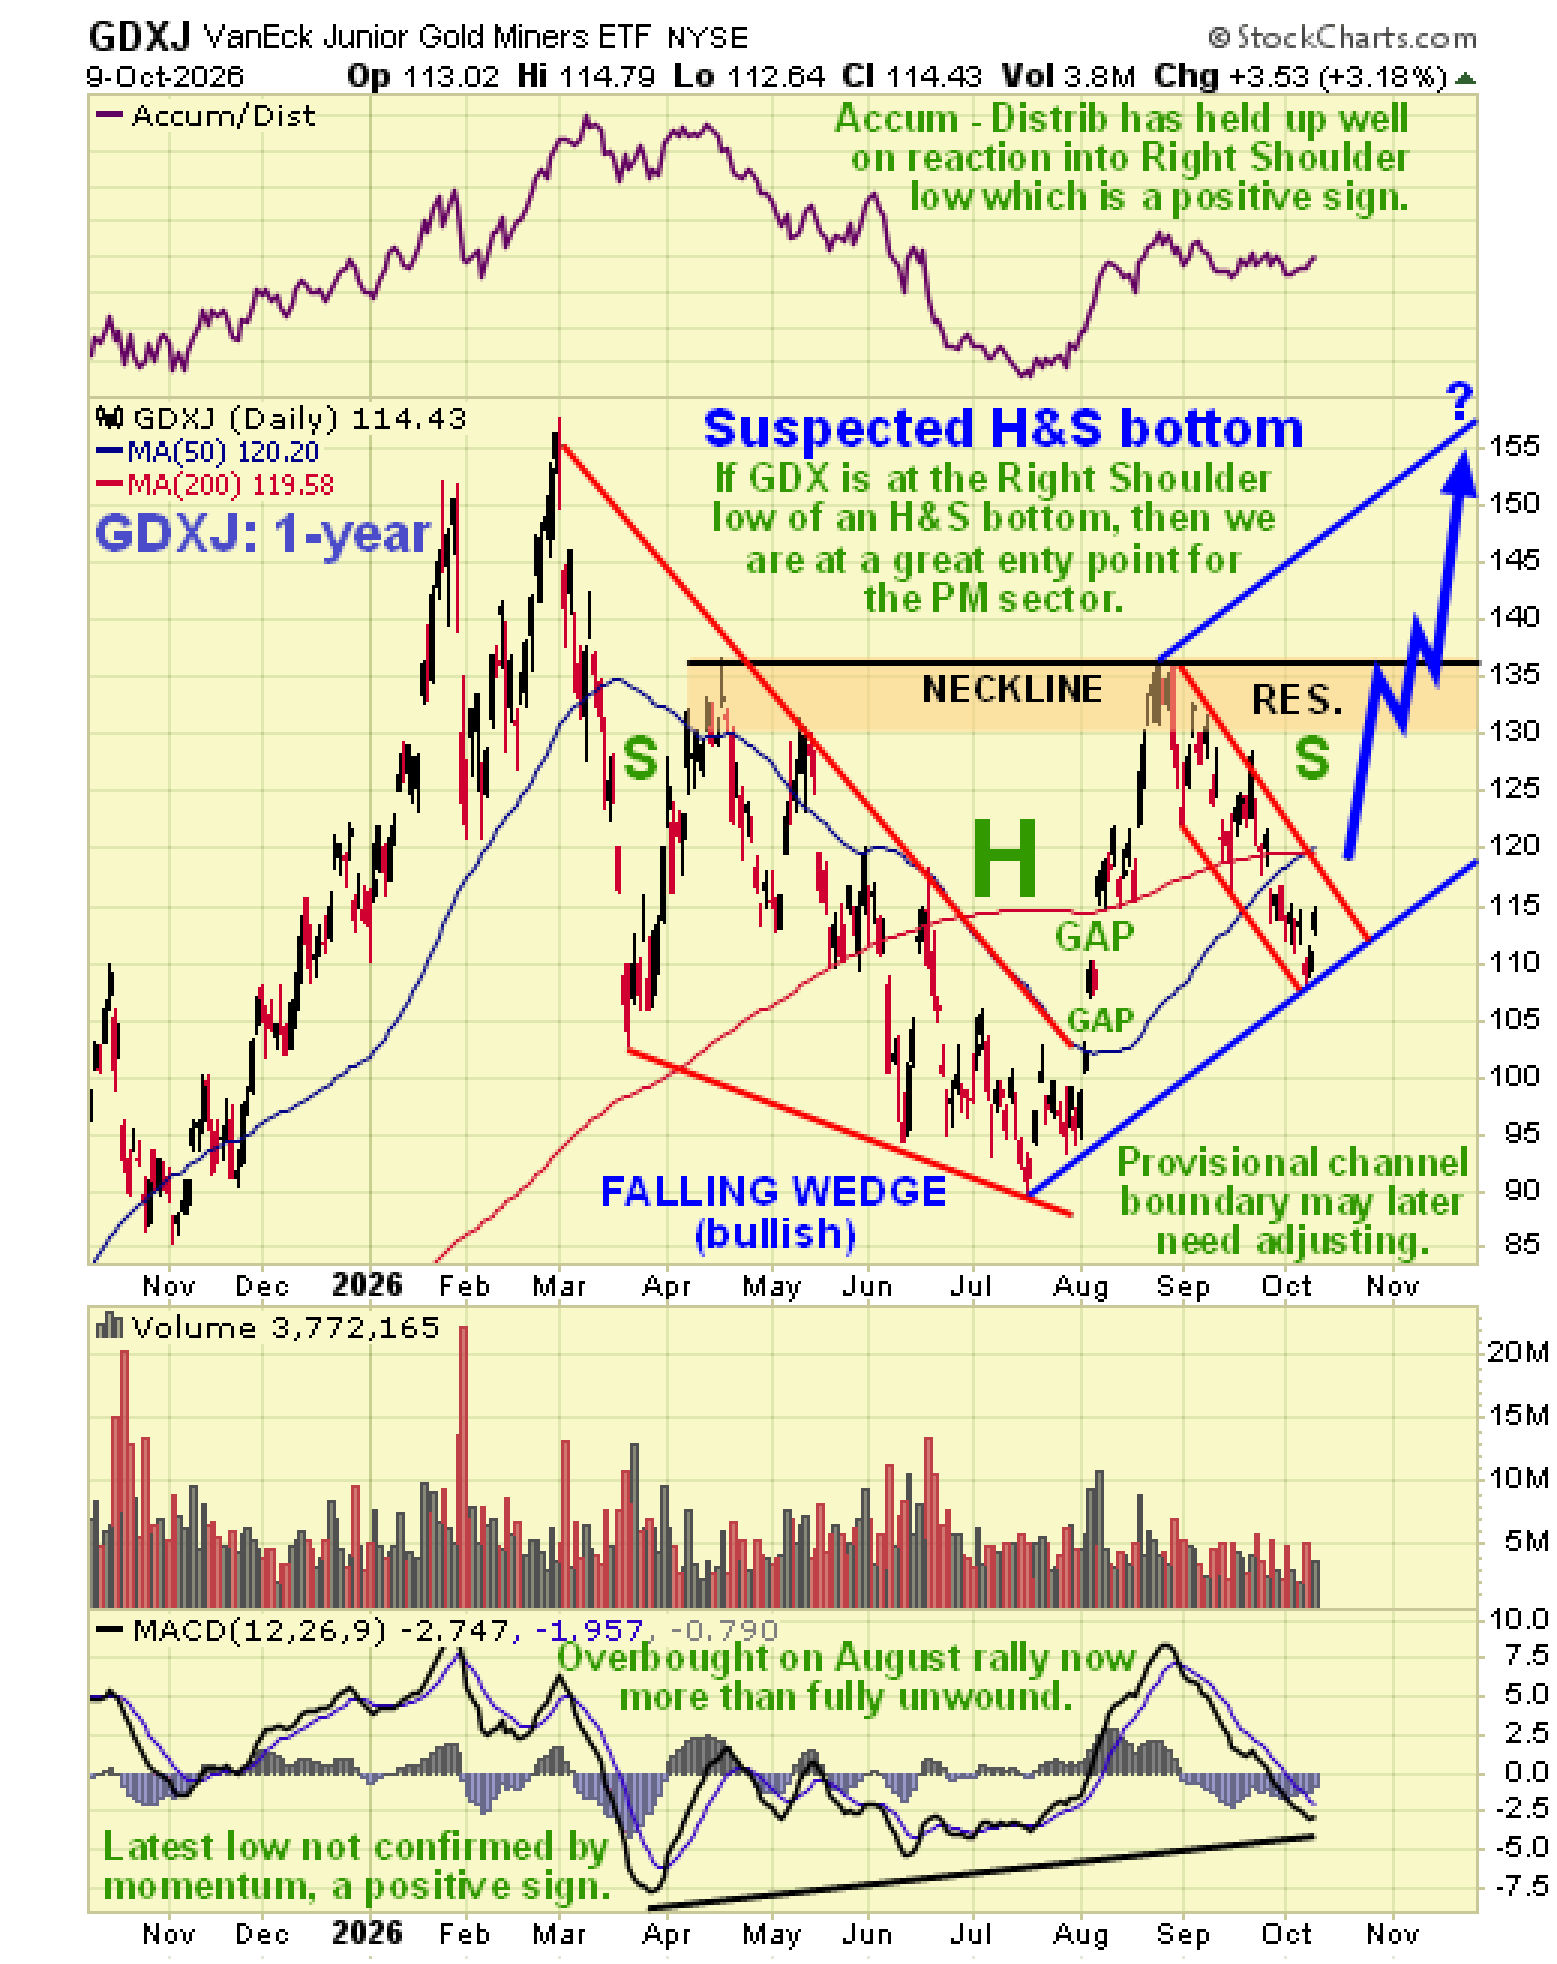
Bearing all of the above in mind we will now proceed to review 1-year charts for the VanEck Gold Miners ETF (GDX) and the VanEck Junior Gold Miners ETF (GDXJ). On both these charts we saw a decisive breakout in August from their strongly converging and thus correspondingly bullish Falling Wedge corrections from their late February highs (they topped out a bit later than gold itself). The breakouts were followed by a strong advance with high volume gaps which are bullish and the subsequent corrections back look normal and proportionate and synchronized with the recent steep runups in the dollar and rates which as we saw above now look to have run their course. So the reaction back from late August in both GDX and GDXJ and a number of stocks now looks like prices dropping back to mark out the Right Shoulder low of Head-and-Shoulders bottoms, as drawn on the charts.
IF THIS INTERPRETATION IS CORRECT, IT MEANS THAT WE ARE AT A GREAT POINT TO BUY THE SECTOR NOW OR ADD TO POSITIONS.
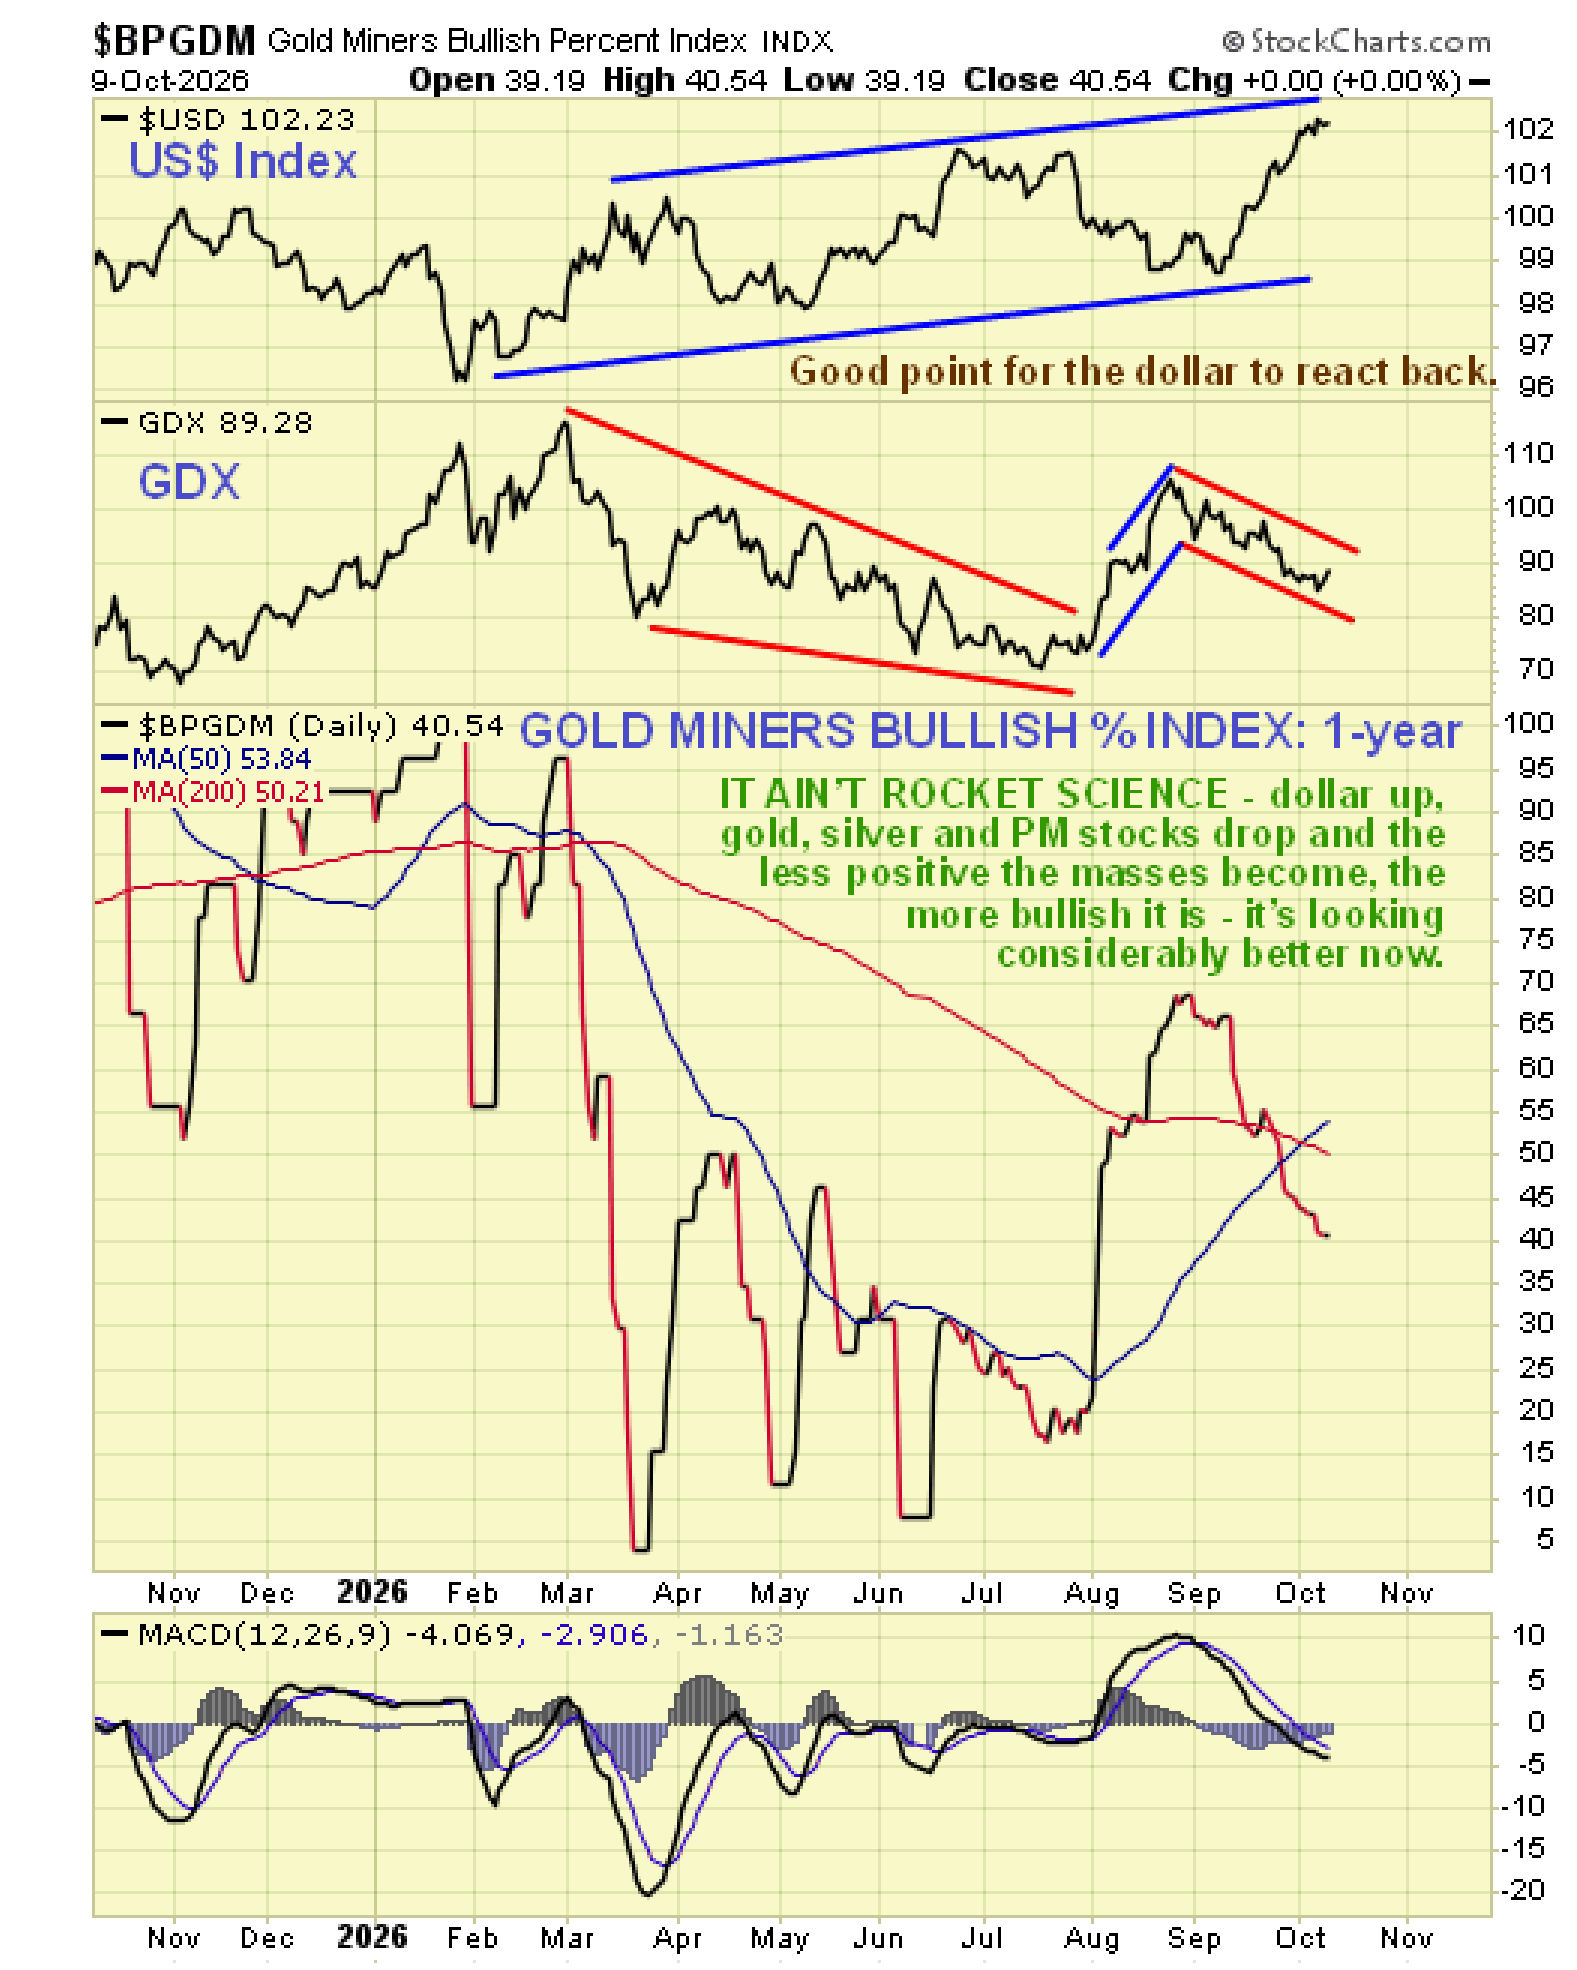
Over a month ago we definitely did not like the high reading of the Gold Miners’ Bullish % Index at about 68% (as in “too many dummies are getting rich”) but now it has moderated to a much more reasonable 40.5% thus opening the door more to renewed advance as we can see on its latest 1-year chart below...
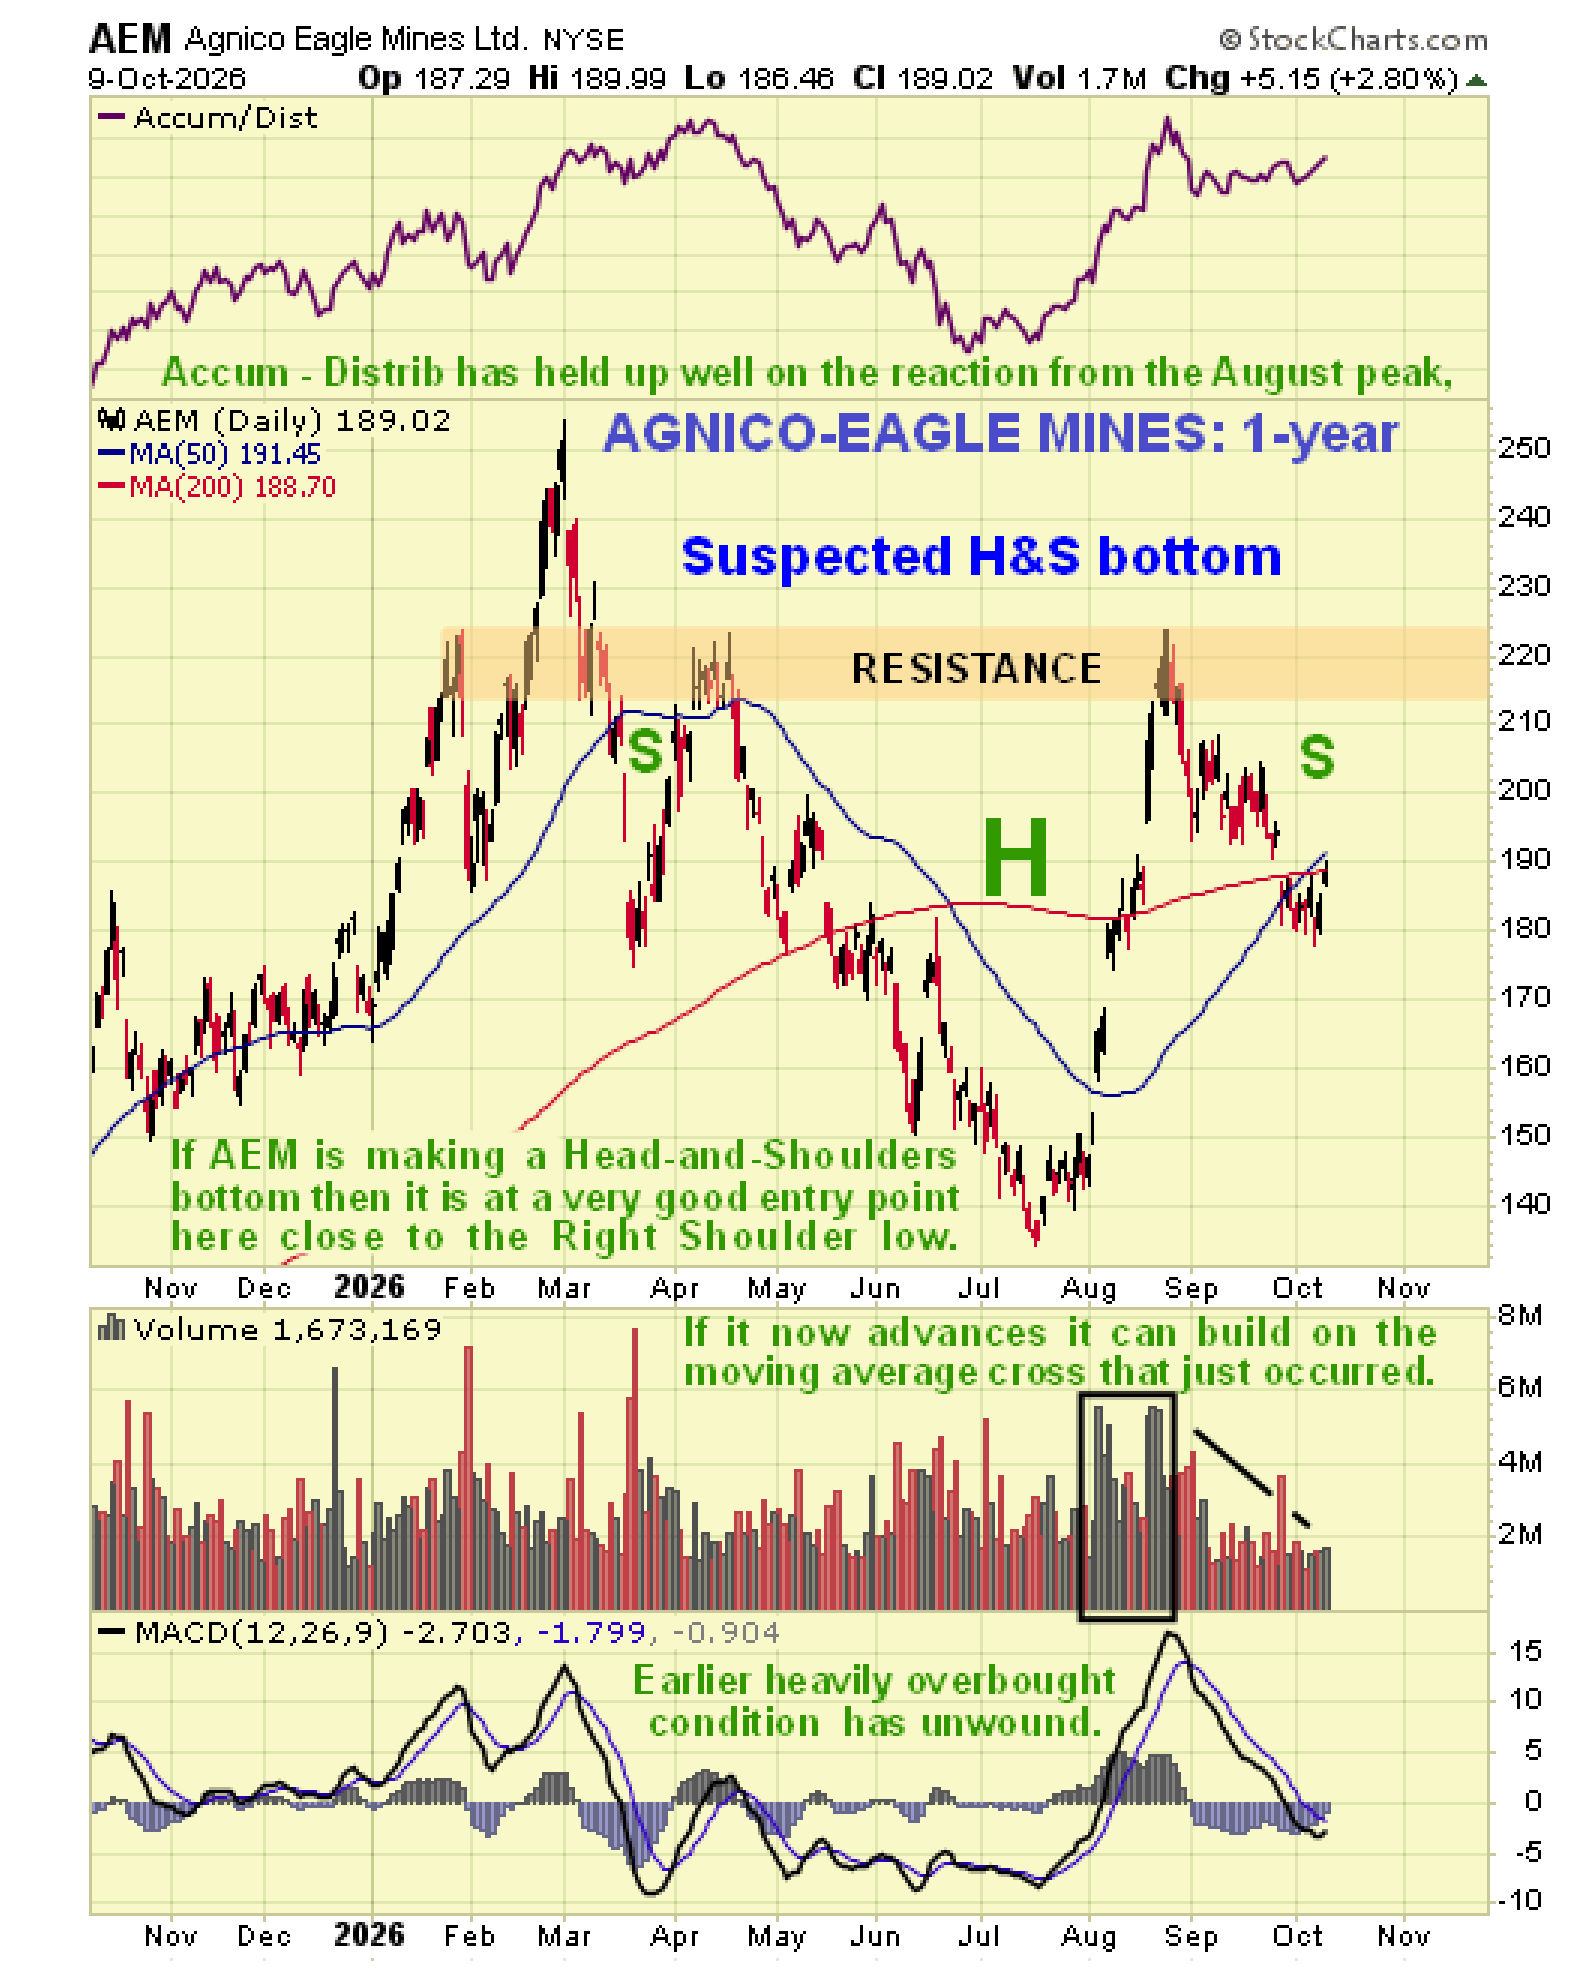
Lastly, by way of practical application of what we have observed above, we will take a quick look at the chart of big gold miner Agnico-Eagle. On its 1-year chart we can see a fine example of what should prove to be a Head-and-Shoulders bottom with the chances of it being this greatly improved by the heavy volume on the advance to complete the right side of the Head of the pattern and the buoyant Accumulation line shown at the top of the chart which has held up well on the reaction from the late August peak.
A fundamental factor that could have an immediate positive bearing on the situation is Trump’s sudden conciliatory moves towards Putin and Russia. Trump said that the leader of Ukraine was responsible for keeping the war going and that Russia could export much needed diesel to the US without penalty. This change of attitude could defuse tensions leading to lower oil prices and to the dollar and rates correcting back for a while which would clearly provide a tailwind for the PM sector.
End of update.
Posted at 8.50 pm EDT on 10th October 26.